I approached DailyPay On-Demand Pay as a practical finance app rather than a general budgeting tool. Its purpose is narrow but useful: it helps eligible workers access wages they have already earned before the normal payday arrives. That makes it most relevant when the problem is timing, not income. If a bill, grocery trip, transport cost, or small emergency arrives before payday, earlier access can be more useful than advice about saving money.
The app is free to install, is listed for Everyone, and comes from DailyPay Inc. It has built a sizeable audience, with over one million installs, a 4.7 average from around 238 thousand ratings, and roughly 19 thousand written reviews. Those figures suggest that the basic idea is easy for many people to understand, although popularity should not be confused with universal eligibility or a guarantee that the app will suit every employer and pay arrangement.
How DailyPay fits into real payday decisions
In everyday use, the important distinction is between earned wages and a loan. The app is designed around accessing pay that has already been earned, rather than borrowing against a future salary in the usual sense. That distinction matters because a worker may need help covering a short gap without wanting to apply for a credit product or put a purchase on a card.
My first recommendation would be to treat it as a timing tool, not extra money. If I used it, I would decide in advance what problem the withdrawal solves and how much of my available earnings I actually need. That simple habit keeps the app from turning an occasional cash-flow issue into a routine that leaves the next payday feeling smaller.
The experience is also dependent on the employment setup behind the account. DailyPay is not simply a universal wallet that can release wages from any job. A worker needs an arrangement that supports the service, and the amount available can relate to earnings information received through that arrangement. In other words, downloading the app is only the first step; the useful question is whether the person’s employer and payroll situation work with it.
What the free price really tells you
The app itself is free, which removes the usual download barrier. That is helpful for someone who wants to inspect whether the service fits their work situation before committing money to an installation. Still, “free app” should not automatically be read as “every possible use is free.” Accessing an app at no purchase price and understanding any transaction choices are separate questions.
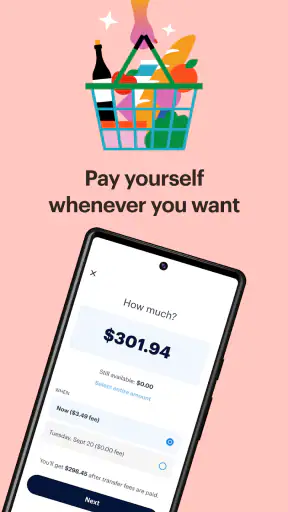
I would therefore look carefully at the amount shown before confirming a transfer, especially when I needed only a small sum. The practical value depends on how much of the earned wage can be accessed, how quickly it arrives through the selected method, and whether any option presented during the transaction changes the final value. Those are the details that matter more than the download price.
This is also why DailyPay should be compared with the cost of the alternative, not merely with other apps. If the alternative is an overdraft, a late bill, or a high-cost short-term credit product, early wage access may feel worthwhile. If the alternative is simply waiting a few days and keeping the full paycheck intact, waiting may be the better financial decision.
A realistic use case: the week before payday
Imagine I have already worked most of the pay period, but my car needs fuel for the remaining shifts and a household bill is due before payday. I could use DailyPay to address the immediate gap instead of borrowing from a friend or using a credit card. Once the urgent expense is covered, I would stop there rather than treating the remaining available balance as spending money.
The useful workflow is to open the app when there is a specific need, check the amount available, compare the delivery choices shown, and withdraw only what solves that need. I would then record the withdrawal in my personal budget as money already taken from the upcoming paycheck. That last step is easy to overlook, but it prevents the next payday from appearing mysteriously short.
There is a less obvious trade-off in this scenario. Early access can reduce stress today while creating a tighter budget later. If the same rent, food, and transport costs still arrive after payday, taking wages early has not reduced those obligations; it has only moved part of the cash flow forward. The app is strongest when it handles a temporary mismatch, not when it is used to cover a permanent monthly shortfall.
What I found useful about the experience
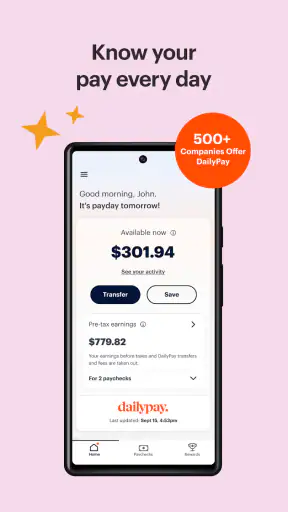
The focused purpose is its biggest strength. I do not have to use DailyPay as a full financial planning system to understand why I opened it. The central question is straightforward: how much of my earned pay can I access now, and what will that help me handle? For workers who regularly face expenses between paychecks, that directness is more useful than a crowded collection of unrelated financial tools.
It can also be a better fit than a traditional credit application when the need is short-lived and tied to wages already earned. A credit card or overdraft may remain available after the immediate expense, which can make repeated borrowing easy. DailyPay’s connection to earned pay keeps the decision closer to the actual work and pay cycle, although it does not remove the need for discipline.
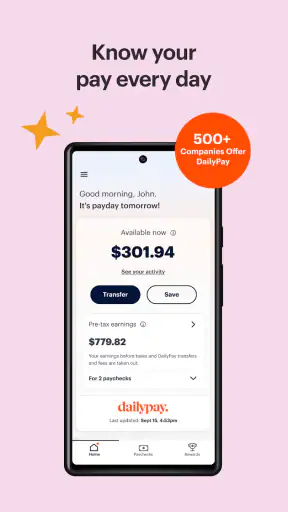
Another practical advantage is that the app can encourage more deliberate decisions than an informal cash advance. I can see the available amount before deciding whether to take anything. That creates an opportunity to ask, “Do I need this now, or am I simply tempted because it is visible?” Used carefully, that pause is valuable.
The app’s age rating also makes it broadly approachable from a store perspective, but that should not be mistaken for a promise that every adult worker can use it. Employment eligibility, payroll compatibility, and the user’s own circumstances remain more important than the general content rating.
Where the value becomes less clear
The free installation is not enough to establish that every transfer is the best-value option. I would pay attention to the final confirmation screen and compare the available delivery methods before proceeding. A fast transfer can be attractive during an emergency, but speed is only valuable if it solves a genuine time-sensitive problem. For a non-urgent purchase, a slower or no-cost route may make more sense if one is offered.
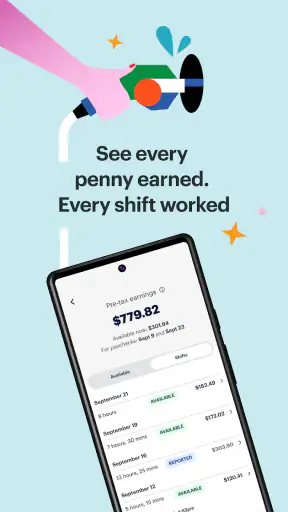
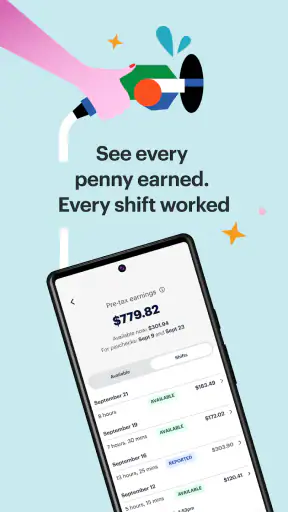
I would also avoid planning my regular bills around the maximum amount displayed. Available earned wages are not the same as disposable income. Taxes, deductions, rent, subscriptions, and ordinary spending still need to be covered. The visible balance can make a worker feel wealthier than the full pay cycle actually allows, particularly when several withdrawals are made.
Another limitation is that the app cannot fix insufficient earnings. If someone is repeatedly short before payday because their income does not cover essential expenses, early access may provide relief but not a solution. In that case, a budgeting conversation, a benefits check, a change in payment dates, or a more sustainable income plan may be more important than another withdrawal.
There is also a human-factors issue. Convenience can make repeated use feel harmless. I would set a personal rule, such as using the service only for defined necessities and reviewing the next paycheck after every withdrawal. The app may make the transaction simple, but the financial consequences still belong in the user’s wider budget.
How it compares with ordinary alternatives
Compared with waiting for payday, DailyPay offers flexibility but reduces the amount left to receive later. Waiting costs no access to earned wages today, yet it may be impossible when an essential expense cannot be postponed. The right choice depends on whether the timing problem is urgent enough to justify changing the normal pay rhythm.
Compared with a credit card, early wage access may feel more connected to money already earned, while a card can create a balance that survives beyond the next pay period. A card may still be preferable for someone who needs purchase protections, a longer repayment structure, or a payment method accepted where a wage-access transfer is not useful. DailyPay is not a replacement for every function of a card.
Compared with an overdraft, the app may offer a more intentional way to handle a shortfall because the user is looking at earned pay rather than simply allowing a bank balance to fall below zero. However, an overdraft may be automatic or already integrated into a person’s account, so convenience alone does not decide the comparison. I would compare the actual consequences of each choice before using either one.
Compared with borrowing from family or friends, DailyPay can preserve privacy and avoid an awkward repayment conversation. The trade-off is that it still changes the timing of personal income and may involve transaction choices that deserve attention. Compared with a payday loan, the wage-based approach may be more appropriate for a worker facing a brief gap, but I would still read every confirmation detail rather than assuming that the label alone makes a transaction cost-free.
Small habits that make the app safer to use
My first habit would be to name the expense before opening the app. “Groceries for the next two days” is a useful purpose; “I have money available” is not. This turns the app from an impulse button into a targeted cash-flow tool.
Second, I would check the upcoming payday budget immediately after taking money. I would write down the amount withdrawn and subtract it from the expected usable paycheck, not from the headline wage. That distinction matters because the amount that reaches a bank account can differ from the gross amount earned after ordinary deductions.
Third, I would compare urgency with delivery speed. If the expense is due tomorrow, faster access may have a clear purpose. If it is for a purchase that can wait, I would pause and see whether waiting for the normal payday avoids unnecessary cost or reduces the risk of overspending.
Fourth, I would avoid using the displayed availability as a target. A responsible withdrawal can be much smaller than the maximum shown. Keeping a buffer for transport, food, and unexpected needs is more useful than emptying the available amount simply because the option exists.
Finally, I would review the pattern after a month or two. If I keep opening DailyPay for the same bill, the issue is no longer an isolated timing problem. That is a signal to revisit the budget or payment schedule rather than increasing reliance on early access.
Who is likely to get the most value
I think the best match is a worker with a participating employment arrangement, fairly predictable pay, and an occasional gap between earned income and an essential due date. For that person, the app can provide a controlled alternative to a credit card, overdraft, or personal favor. The free download also makes it reasonable to investigate the service without paying upfront for the app itself.
It may also suit someone who wants a clear separation between ordinary banking and a wage-access decision. Instead of carrying a credit balance or asking a bank to extend funds, the user can consider a portion of pay already earned. That can make the decision easier to explain to themselves, provided they remember that the next paycheck will reflect the earlier withdrawal.
I would be more cautious for anyone whose income is irregular, whose essential expenses consume nearly the entire paycheck, or who already relies on frequent advances. The app can be useful in a genuine emergency, but repeated use in those circumstances may deepen the cycle of shortage. Someone looking for investing tools, detailed spending analysis, debt payoff planning, or a complete bank replacement should also look elsewhere; DailyPay’s role is much narrower.
Current app details and overall judgement
DailyPay Inc released the app on December 7, 2018, and the current version is 52.0.0. It supports devices running iOS or Android 9 and newer, which is worth checking before installation if an older phone is still in use. The product remains free to download and is categorized as a finance app, so its value should be judged by the quality and suitability of its wage-access use case rather than by the number of extra financial tools someone might expect from a banking app.
My verdict is positive but conditional. DailyPay is most valuable when it solves a specific, short-term timing problem without becoming part of the monthly spending plan. I would recommend trying it to an eligible worker who needs occasional access to earned wages and is prepared to check the final transaction details, protect the next paycheck, and withdraw only what is necessary.
I would skip it if the goal is simply to spend more before payday, if waiting is realistic, or if recurring cash shortages are already normal. The free price makes exploring the app easy, but free access does not remove the financial trade-off of moving wages forward. Used with a clear purpose, it can be a practical safety valve; used automatically, it can make an already tight pay cycle harder to manage.
After using it, I would keep one question in mind: did the withdrawal solve an unusual timing issue, or did it become necessary to make ordinary life work? If the answer is the first, DailyPay can be a sensible tool. If it is the second, the better next step is a broader financial fix, not simply another early payday.


